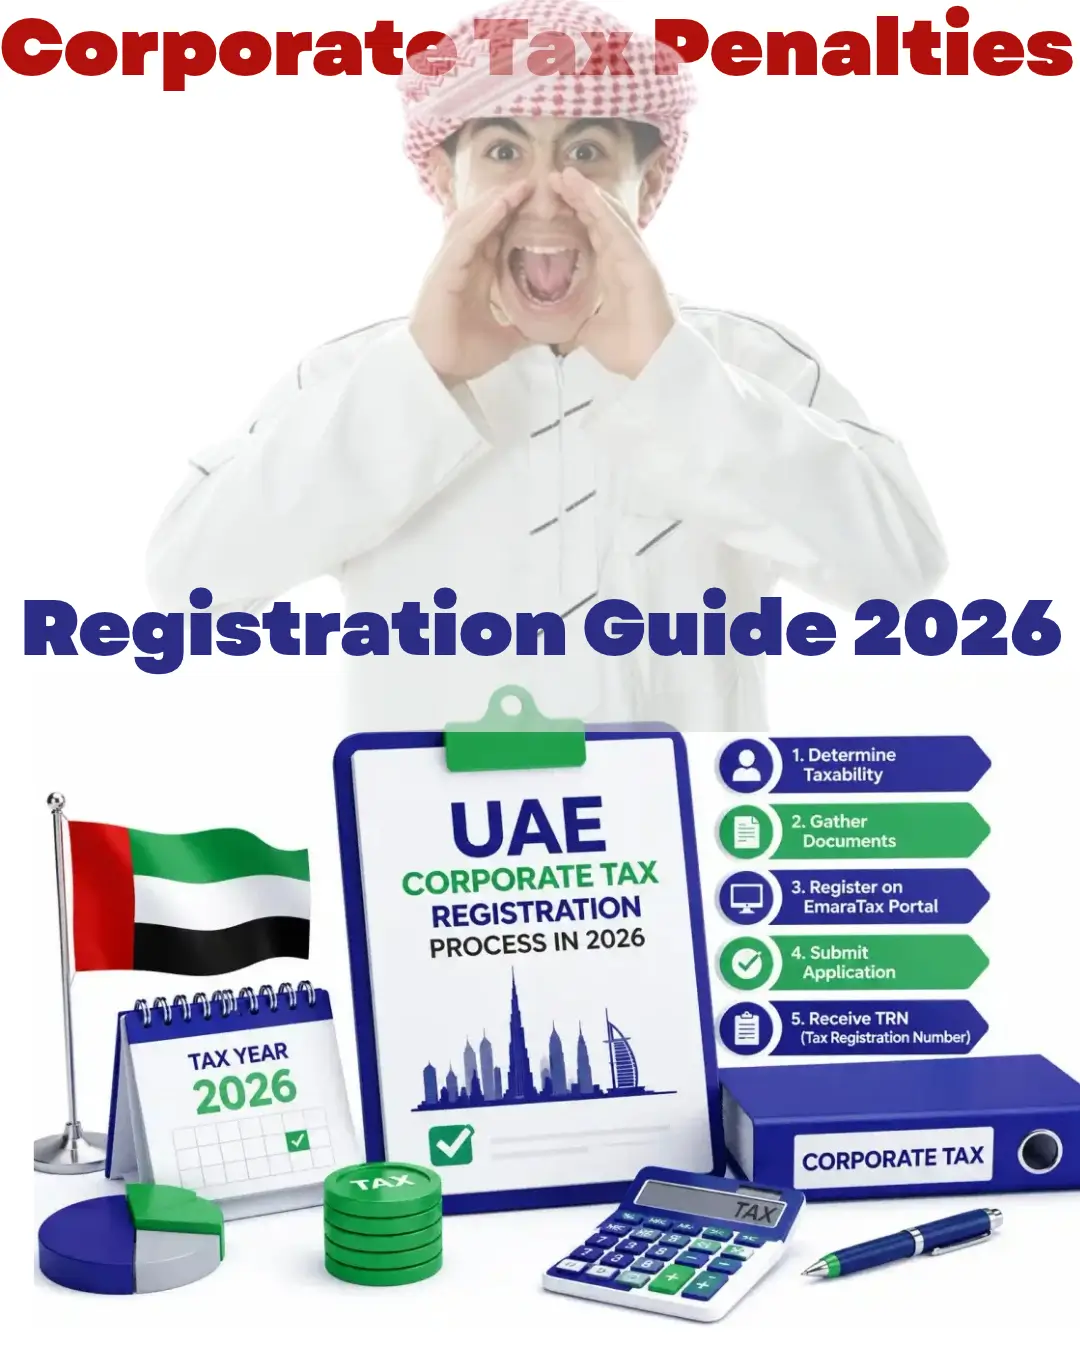
Missing a UAE corporate tax registration deadline can be expensive. The Federal Tax Authority (FTA) confirms that the administrative penalty for late registration is AED 10,000. However, the position may not be final: an official penalty-waiver initiative provides relief to eligible businesses that meet specific conditions.
For small business owners in Dubai and Sharjah, the first step is to establish which obligation was missed. Registering late, submitting a tax return late and paying tax late are separate compliance issues. Each must be checked against the rules that apply to the business.
This guide explains the main penalties, the registration waiver, common mistakes and the practical steps to take if a deadline has passed. It uses official FTA information available as of October 2026.
Important: This article provides general information, not tax advice. Confirm your circumstances with the FTA or an appropriately qualified UAE tax professional before making a tax decision.
What is the penalty for late corporate tax registration in the UAE?
The FTA’s published corporate tax registration service states that the administrative penalty for late registration is AED 10,000.
The amount is relevant to businesses and other persons required to register who fail to submit their registration application within the prescribed timeframe. The exact deadline depends on the taxpayer’s category and circumstances.
The FTA also operates a late-registration penalty-waiver initiative. Eligible taxpayers may qualify by completing the required registration procedures and submitting their first corporate tax return, or an applicable annual declaration for an exempt person required to register, within seven months from the end of the first tax period or financial year.
Do not assume that every late registration will automatically qualify. Check the applicable conditions and the end date of the first period.
Official reference: FTA corporate tax registration and penalty information.
What counts as late registration?
A business is late when it fails to submit its corporate tax registration application within the timeframe that applies to it.
The deadline is not necessarily the same for every business. Legal form, residence status, licence or establishment dates and other relevant circumstances can affect the applicable rule.
Mainland and free-zone companies
A company operating in Dubai or Sharjah should not assume that its local business licence alone determines its tax registration deadline.
Free-zone status also does not automatically remove corporate tax registration obligations. The FTA’s published registration guidance includes resident juridical persons, including free-zone persons, within the registration framework.
For companies established on or after 1 March 2024, the applicable rules generally require resident juridical persons to apply within three months of incorporation, establishment or recognition. Specific rules apply to other categories, including certain non-resident persons.
The older registration timetable for businesses established before March 2024 included deadlines during 2024. Those dates are historical. They should not be reused as the current deadline for a newly established business.
If you hold multiple licences, have an expired licence, operate through a branch or manage a business incorporated abroad, check the relevant FTA guidance rather than relying on a general rule.
Official reference: FTA registration timelines and public clarification.
Sole establishments and individual business owners
An individual carrying on a business in the UAE may also have corporate tax registration obligations.
For a natural person, the general threshold is business turnover exceeding AED 1 million within a calendar year. Wages, personal investment income and real estate investment income are excluded from the relevant business-activity calculation under the FTA’s published guidance.
This is not a rule that applies identically to every legal entity. A limited liability company and an individual conducting business must be assessed under their respective rules.
Official reference: FTA basis of taxation for natural persons.
Registration, filing and payment: understand the difference
One of the most costly mistakes is treating every tax deadline as the same obligation.
| Compliance issue | Official position | What to check |
|---|---|---|
| Late registration | AED 10,000 administrative penalty | Applicable registration deadline and possible waiver eligibility |
| Late tax return | AED 500 per month or part of a month for the first 12 months; AED 1,000 per month or part thereafter | Return due date and date of submission |
| Late payment | Separate administrative penalty rules apply | Amount due, payment deadline and applicable penalty calculation |
| Small Business Relief | Relief from taxable income treatment when eligible and properly elected | Revenue history, taxpayer status and filing requirements |
The late-return amounts above are stated in the FTA’s published guidance on return filing and payment deadlines. They are not additional charges that should automatically be added to every late-registration case.
Corporate tax returns and applicable payments are generally due within nine months of the end of the relevant tax period. That ordinary deadline differs from the seven-month condition associated with the late-registration penalty waiver.
Official reference: FTA guidance on filing and payment deadlines.
Can the FTA waive the AED 10,000 registration penalty?
Yes, the FTA has published a waiver initiative for eligible cases. It is particularly important for businesses that discovered the registration problem after the original deadline.
The initiative covers eligible persons who registered late, have not yet submitted a registration application, or have already been charged the penalty, whether or not they paid it.
The central condition is that the taxpayer must submit the first tax return within seven months from the end of the first tax period. For an exempt person required to register, the applicable annual declaration must be submitted within seven months from the end of the first financial year.
This seven-month condition applies to the first period. It should not be confused with the ordinary nine-month filing deadline.
What if you have already paid the penalty?
The FTA’s published guidance explains that an eligible taxpayer who has paid the penalty may receive a credit to the corporate tax account after meeting the waiver conditions. The taxpayer may then use the credit against eligible tax liabilities or pursue a refund through the applicable process.
Do not assume that payment makes the waiver unavailable. Equally, do not assume that a refund is automatic without first satisfying the conditions.
What should you do if you have not registered yet?
Check the registration requirements and submit the application promptly if required. Then establish the end date of the first tax period and calculate the seven-month waiver deadline.
Keep copies of the application, registration confirmation, return submission and relevant correspondence. If your first-period deadline may already have passed, obtain case-specific guidance from the FTA or a qualified tax professional.
Official reference: FTA penalty-waiver initiative.
Does Small Business Relief remove the registration requirement?
No. Small Business Relief and corporate tax registration are different matters.
Under the FTA’s published guidance, eligible resident natural persons and juridical persons may elect for Small Business Relief when revenue is no more than AED 3 million in the current and all previous tax periods, subject to the applicable conditions. The rules exclude certain categories, including Qualifying Free Zone Persons and members of multinational groups above the specified consolidated revenue threshold.
Eligible taxpayers are treated as having no taxable income for the relevant period when the relief applies. That does not mean the business can ignore registration, return submission or record-keeping obligations.
For example, a small Dubai consultancy might qualify for relief based on its revenue history but still need to register and file its required return. An individual running a business in Sharjah must separately consider the natural-person threshold and rules.
Check the current requirements before relying on relief.
Official reference: FTA corporate tax topics and Small Business Relief.
Common mistakes that put small businesses at risk
1. Assuming low revenue means no registration
Low revenue alone is not a universal exemption from corporate tax registration. The applicable rules depend on whether the business is a juridical person, a natural person or another category.
Better approach: Identify the legal form first, then check the relevant FTA registration rules.
2. Treating free-zone status as a complete exemption
A free-zone company may have a different tax treatment for particular purposes, but free-zone status does not automatically eliminate registration obligations.
Better approach: Check the registration requirements separately from the rules for qualifying free-zone tax treatment.
3. Confusing the seven-month and nine-month deadlines
The ordinary return deadline and the late-registration waiver deadline serve different purposes.
Better approach: Record both dates and work from the end of the first tax period, not just from the date you discovered the problem.
4. Waiting for an accountant to identify the problem
Professional assistance can be useful, but waiting without checking your own records can cost valuable time.
Better approach: Gather your licence, incorporation documents, financial-year details and FTA correspondence now. Share them with your tax adviser if you need help determining the applicable deadline.
5. Assuming payment ends the matter
Paying a penalty does not necessarily resolve other outstanding filing or payment obligations. It also does not automatically prevent an eligible taxpayer from receiving the benefit of the published waiver.
Better approach: Reconcile your registration status, tax returns, payments and account balance separately.
6. Ignoring official messages
An FTA notification may contain a deadline, an outstanding action or information about a penalty.
Better approach: Read the message carefully, preserve the correspondence and verify your position through the official EmaraTax account.
A practical recovery checklist
If you suspect your business registered late, use the following sequence.
- Identify the taxpayer. Confirm whether the business is a company, a free-zone entity, an individual carrying on business or another category.
- Find the relevant dates. Gather incorporation or establishment documents, licence details, financial-year dates and any relevant changes in legal status.
- Check the deadline. Use the applicable FTA registration rule rather than relying on another company’s timetable.
- Review the registration status. Check whether an application was submitted, whether a tax registration number was issued and whether the FTA has recorded a penalty.
- Submit any outstanding registration application. If registration is required and remains incomplete, address it promptly.
- Calculate the first-period waiver deadline. Establish the end date of the first tax period or first financial year and determine whether the seven-month condition remains available.
- Complete the required return or declaration. Follow the rules that apply to your taxpayer category.
- Reconcile separate liabilities. Check outstanding returns, corporate tax payments and penalties independently.
- Keep evidence. Save submissions, confirmations, payment records and relevant FTA correspondence.
- Get professional help where needed. Seek case-specific advice if the applicable deadline, taxpayer classification or waiver eligibility is uncertain.
For further background, see the UAE corporate tax guide for small businesses.
Two illustrative cases: how earned trust works in practice
The following examples are hypothetical. They are not accounts of actual clients, and they do not establish that a waiver will be granted in any particular case.
Case 1: A small consultancy in Dubai
Imagine a Dubai consultancy that discovers its registration application was not submitted by the applicable deadline. Its owner is concerned about the AED 10,000 penalty.
The first responsible step is not to promise that the penalty will disappear. The owner should establish the correct registration deadline, complete any outstanding registration requirements and determine the end date of the first tax period.
The owner must then check whether the first return can be submitted within the seven-month waiver period. If the conditions are met, the business may qualify under the FTA’s published initiative.
Trust lesson: Reliable advice starts with documents, dates and official conditions. It does not begin with a guarantee.
Case 2: An individual business owner in Sharjah
Imagine a Sharjah-based individual who conducts business and assumes that low profits mean corporate tax registration is unnecessary.
The correct assessment begins with turnover from business activities, not simply profit or the amount of tax the owner expects to pay. The owner must determine whether the natural-person rules apply, whether the turnover threshold has been exceeded and which registration deadline follows.
If the individual has an outstanding registration obligation, the next steps are to confirm the relevant dates, submit the required application and check any applicable relief.
Trust lesson: The correct answer depends on the taxpayer’s legal category and facts. A general statement about small businesses cannot replace that assessment.
These examples illustrate a method, not verified personal experience. If Abu Ubaida has actually handled cases of this kind, a genuine case study can be added after confirming the facts, dates, outcome, supporting records and permission to publish.
How to avoid another compliance problem
Once the immediate issue is addressed, create a basic tax compliance calendar.
Record the end of each tax period, the ordinary return deadline, the relevant payment deadline and any additional deadline that applies to a relief or waiver. Assign a responsible person to check FTA notifications and retain submission confirmations.
A business operating across Dubai and Sharjah should use the same disciplined process even if its licensing arrangements differ. The key is to track the rules applicable to each taxpayer rather than assuming that the emirate, free-zone status or revenue level settles every question.
Conclusion
The confirmed late corporate tax registration penalty in the UAE is AED 10,000. However, eligible businesses may benefit from the FTA’s penalty-waiver initiative if they satisfy its specific conditions.
The most useful response to a missed deadline is to establish the taxpayer category, verify the relevant dates, complete outstanding obligations and assess the waiver separately from return-filing and payment liabilities.
For current requirements, begin with the FTA corporate tax registration service. This article is general information, not tax advice; obtain professional guidance where your circumstances are unclear.
1. How much is the corporate tax late-registration penalty in the UAE?
The FTA states that the administrative penalty for late corporate tax registration is AED 10,000. Eligible taxpayers may qualify for the FTA’s penalty-waiver initiative if they meet its conditions.
2. What happens if I miss corporate tax registration in the UAE?
First, identify the registration deadline that applies to your business. If the deadline has passed, check your registration status, complete any outstanding application and assess whether the penalty-waiver conditions apply.
3. Can the FTA waive the AED 10,000 penalty?
Yes. The FTA has a waiver initiative for eligible cases. The main condition is submitting the first tax return or applicable annual declaration within seven months of the end of the first tax period or financial year, subject to the relevant rules.
4. What is the corporate tax late-filing penalty in the UAE?
The FTA’s published guidance states that the late-return penalty is AED 500 for each month or part of a month during the first twelve months, rising to AED 1,000 for each month or part thereafter. This is separate from the late-registration penalty.
5. Does Small Business Relief mean I do not need to register?
Not automatically. Small Business Relief has its own eligibility and election requirements. Registration and filing obligations must be assessed separately under the rules applicable to the taxpayer.
6. Does a Dubai or Sharjah free-zone company have to register for corporate tax?
Free-zone status does not automatically remove the registration requirement. The company should check the FTA’s rules for its legal form, establishment date and taxpayer category.
7. Do individual business owners have to register for UAE corporate tax?
Generally, a natural person conducting business in the UAE may be required to register when business turnover exceeds AED 1 million in a calendar year, subject to the applicable rules and exclusions.
8. Is the corporate tax return deadline the same as the penalty-waiver deadline?
No. The ordinary corporate tax return deadline is generally within nine months of the end of the tax period. The late-registration penalty-waiver initiative uses a seven-month condition for the first tax period, subject to its rules.
9. What if I have already paid the late-registration penalty?
The FTA’s guidance states that eligible taxpayers who satisfy the waiver conditions may receive a credit for the penalty paid. Check the applicable conditions and your EmaraTax account for the correct process.
10. What documents should I gather if my business registered late?
Gather your trade licence and incorporation documents, financial-year details, registration application records, tax registration confirmation, tax returns, payment records and FTA correspondence. These help establish the relevant dates and outstanding obligations.
11. Can I fix late registration without hiring a tax agent?
Taxpayers can use the FTA’s official digital services to complete applicable registration and filing procedures themselves. If the taxpayer category, deadline or waiver eligibility is unclear, professional assistance may be appropriate.
12. Where can I verify the latest UAE corporate tax penalties?
Start with the Federal Tax Authority’s official website, particularly its corporate tax registration service, published penalty information and relevant clarifications. Confirm the rules applicable to your own circumstances before acting.